The rate limiter for AI researchers is compute. In the early 2020s, this meant GPU/CPU budgets. However, AI's meteoric rise over the past few years has shifted the bottleneck from the chip to the grid. Substantial capital inflows have led to increasingly high compute budgets for hyperscalers. These have created a scarcity of compute that must be solved by building (and powering) new data centers. While energy infrastructure CAPEX for these data centers is far lower than on the compute side, energy project timelines are a key bottleneck to development. The historic speed, capital, and innovation behind AI therefore pose a direct question to the energy sector: "How can you secure 10 GW in 2 years?"
TAG Capital is a new infrastructure platform with sectoral focuses on advanced energy, manufacturing, and digital infrastructure. At Tierra Adentro, we've been working directly with hyperscalers to find solutions within our advanced energy mandate. Our firm's first two investments (one geothermal project and one solar + ESS) were principally driven by hyperscaler offtake from Amazon and Meta, respectively. We're excited to continue collaborating on building power economically.
Load growth has historically been tied to industrialization and economic development. The clear generational example was the rise of China's economy and US outsourcing. These trends caused US electricity consumption to stagnate over the past 30 years while China rose exponentially (Figure 1). Energy wonks have tended to understate AI's projected impact on load growth. This stems from AI's energy demands defying their established heuristics for power markets. In this absence, various stakeholders have speculated on the market, leading to confusion and a divergence of opinions.
The answer to AI's energy needs is nuanced. The market has aligned on an "all of the above" view, where the rise of AI has led to stock growth for companies spanning fuel cells, flow batteries, renewables developers, turbine manufacturers, and so on. The Trump administration has codified this into an "energy dominance" agenda. This frenzy has led to large business decisions that would have seemed illogical only two years ago, such as purchasing low-efficiency engines en masse for natural gas power conversion. It has also led to large swings in capital markets (Figure 2). Energy stocks are now being traded by speculative retail investors. This is driven by a (now) clear demand with seemingly intractable barriers to serve it appropriately.
1. Rate amortization and other community dynamics. Utilities are semi-regulated monopolies who are focused on growing their businesses by undergoing large power buildouts they can amortize across their ratepayers (as approved by their state-level regulators). Regulators try to force utilities to consider criteria beyond corporate profits and to avoid taking on risk. This dynamic forces utilities to make large CAPEX decisions relatively slowly, such as those required for AI buildout. It also pushes costs onto the ratepayers, which include residences. Utilities have proposed $31b in rate increases over the past 12 months. Home electricity costs and legitimate concerns about community pollution have led to a groundswell of NIMBYism against data centers, and, to a lesser degree, their power sources.
2. Inflexible, unwilling, and compromised supply chains. Global load growth has led to a global shortage across energy supply chains. Many components have inflexible supply chains due to artisan processing or other factors causing long lead times. This is most topical for turbines, but it is also true for inverters, transformers, and increasingly other major components. Energy supply chains are less willing than compute to materially change course to address AI's needs as they have been burned before. Natural gas' share of power capacity additions in the US has been extremely volatile over the past 7 years, fluctuating from 62% of capacity additions in 2018 to 34% in 2019 and to 6% in 2024 (Figures 3-5). Natural gas is once again leading interconnection queues: PJM is currently 48% natural gas. However, it's still unclear if turbine makers see a business case to significantly flex-up capacity. Finally, despite the US inventing key energy innovations like Li-ion batteries and solar PV panels, domestic production capacity is low. Solar and ESS accounted for 84% of new US electricity generation capacity in 2024. However, less than 10% of those ESS cells were made domestically. Additionally, as of 2022, 88% of solar panels were imported. Inverters, transformers, magnets and other components face a similar dynamic. These factors have all stymied hyperscalers' ability to bend energy supply chains to meet AI's needs.
3. Inadequate and inflexible power grid. Many in energy can recount personal horror stories around grid/interconnection challenges. There are 3 core barriers to rapid load growth: 1) many geographies with attractive power resources have inadequate grid infrastructure to support new capacity, 2) grid buildout for power developers is a costly and (more significantly) uncertain process, and 3) large transmission buildout cannot be done in time to meet AI's pressing needs. Many developers consider interconnection their biggest source of insecurity. Major transmission projects take decades rather than years: SunZia is now in commissioning stages after its planning began 20 years ago; Grain Belt Express began development in 2010 and hopes to reach commercial operation date (COD) around 2029. These dynamics have led to various unreasonable interconnection queue dynamics. Topically, large load requests in ERCOT (Texas) rose from 48 GW in May 2024 to 226 GW 18 months later (Figure 7). The key factor with respect to grid capacity is the capacity factor of the power source. This is essentially the percentage of time that it produces power. Grid infrastructure is sized to maximum output; in practice, this means that the same grid infrastructure for a 100 MW, 20% capacity factor solar field could support a 400 MW, 80% capacity factor natural gas power plant.
Various players have taken on the issue of energy for AI, often calling it "time to power." However, no silver bullet has emerged.
Some folks in energy believe that the "fastest MW" could actually come from existing and distributed energy solutions, including project funders, researchers, and former public figures. This makes first-principles sense--there are 40 GW of VPP capacity available today in the US. Unfortunately, functionalizing distributed sources would require multi-level societal coordination that the US has so far been unable to achieve. Realizing headroom from existing capacity requires fewer parties, but it would necessitate novel business and financial structures. Widespread load growth here would also likely require Grid Enhancing Technologies (GETS) for coordination. While it will take time for offtakers, utilities, households, developers, and the US government to align and chart a path forward, there are early signs of progress in Google's 100 MW contract with Voltus for an aggregation of VPPs.
Various other solutions are being suggested or pursued to meet AI's energy needs. Below is an (incomplete) listing. These do not include demand-side approaches, like data center flexibility, novel cooling, or chip-level innovations.
The rapid rise of AI has created an urgent need for power that can't be immediately solved. However, there are a variety of solutions underway and innovations to deliver this power cheaper, cleaner, and more reliably. TAG Capital has been excited to support this buildout through our investments in the Foxtail Flats and Four Mile Mesa solar and battery storage project and in the geothermal power developer Zanskar. We are interested in continuing to support this buildout and would love to connect with folks building in the space.
Figure 1: Global electricity consumption growth
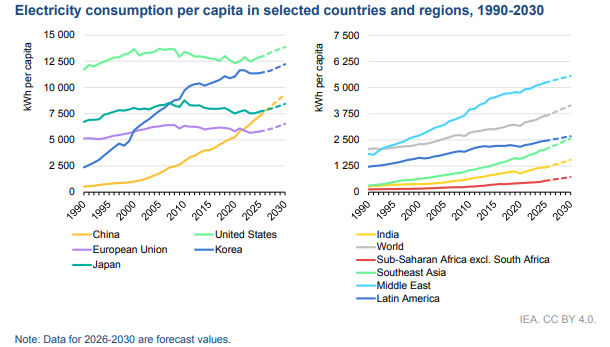
Figure 2: Fermi America's stock price falling
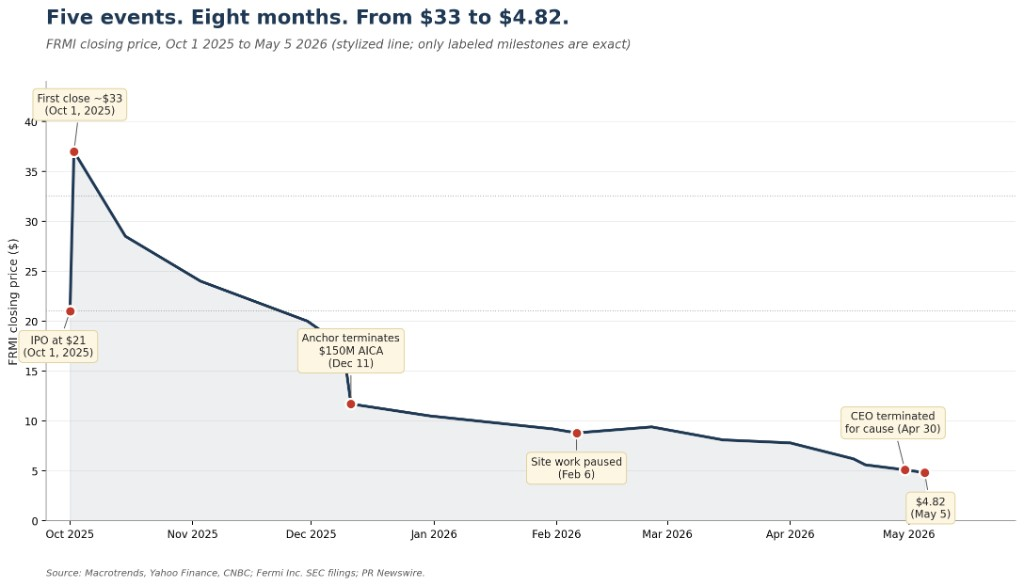
Figure 3: Natural gas accounted for 62% of 2018 capacity additions
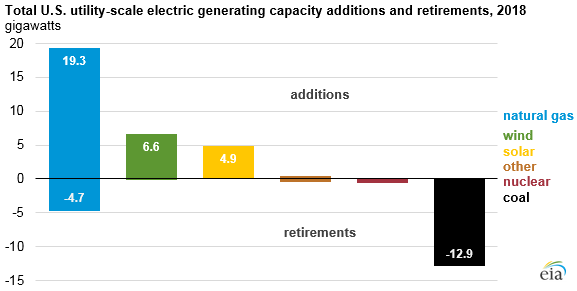
Figure 4: Natural gas % of capacity additions falls to 34% in 2019
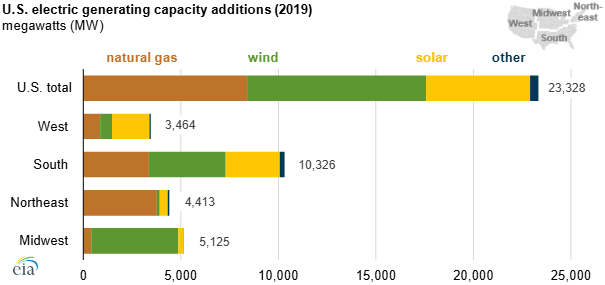
Figure 5: Natural gas % of capacity additions falls to 6% in 2024
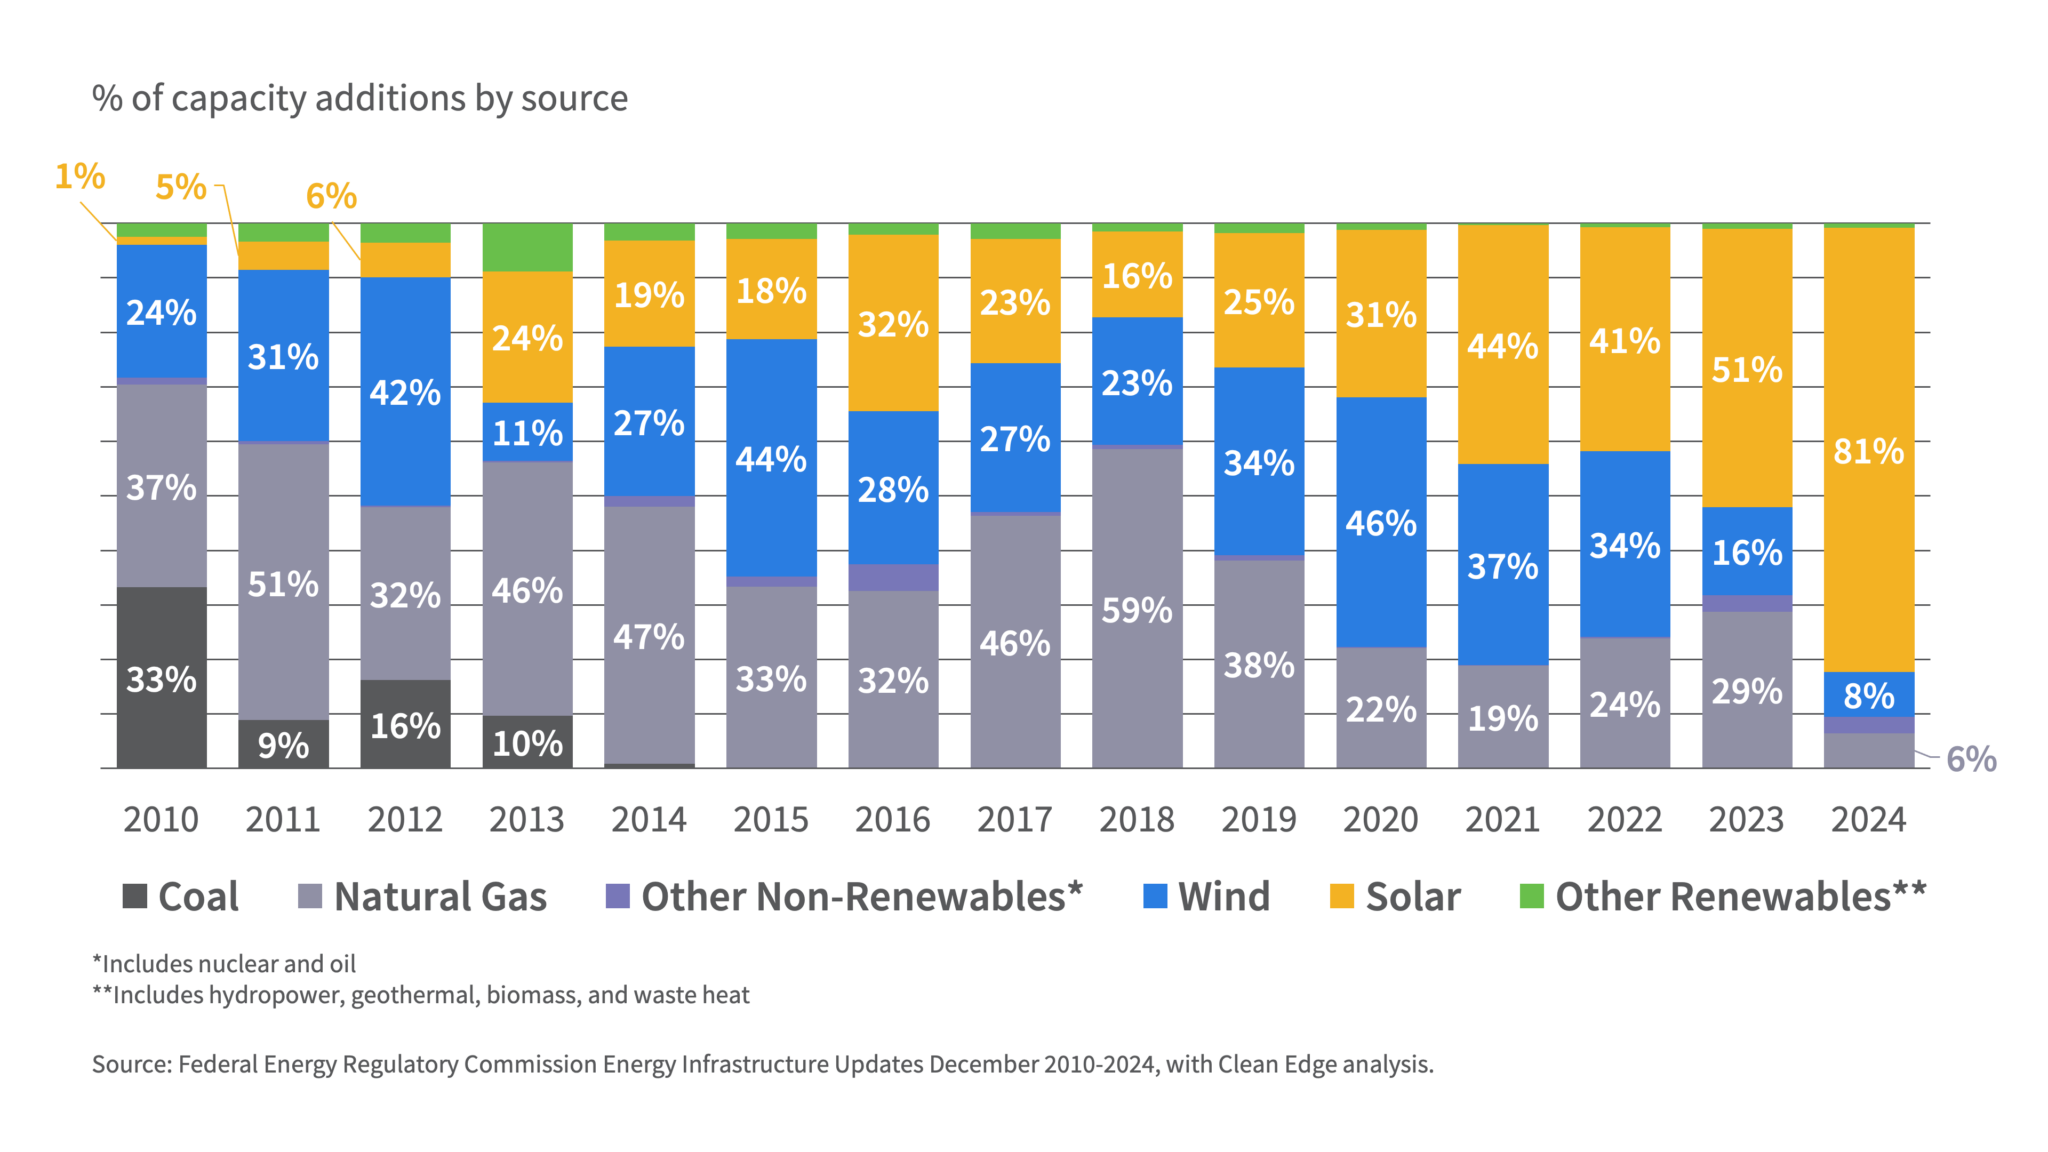
Figure 6: The PJM (Midwest) interconnection queue is 48% natural gas
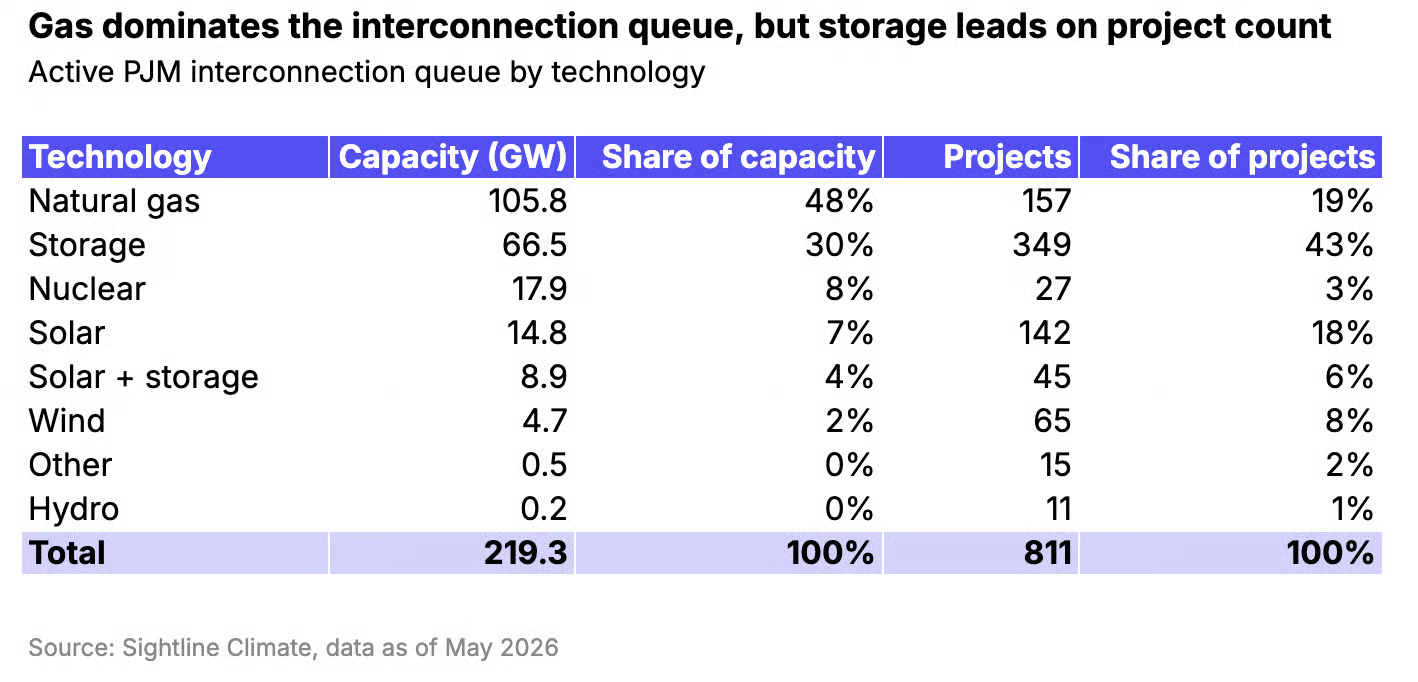
Figure 7: ERCOT's large load interconnection request growth
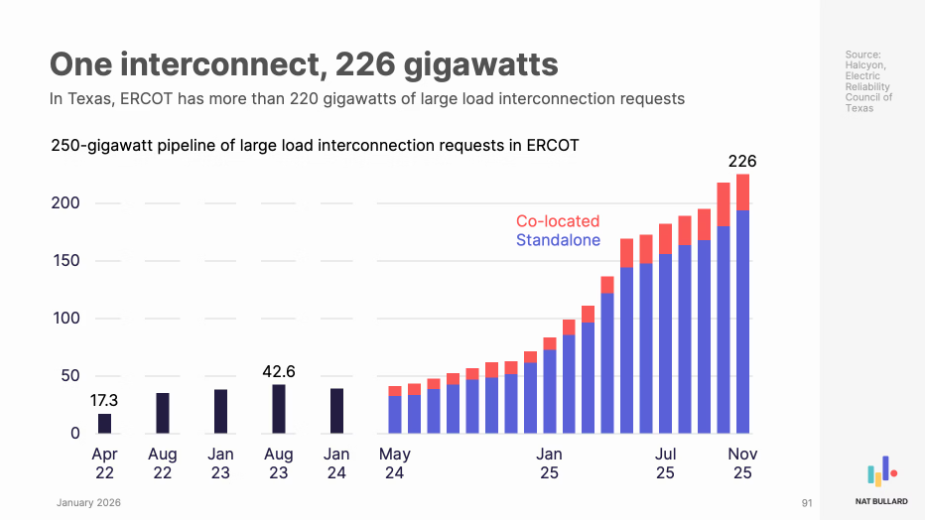
Figure 8: Impact of various sources of energy to residential energy bills
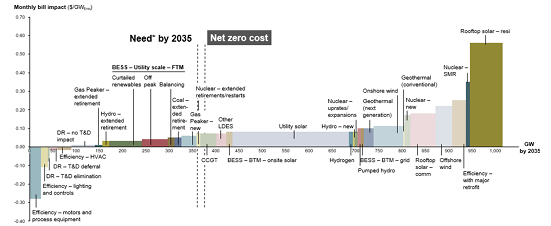
Figure 9: Lithium pricing experiencing immense volatility from 2021 through 2025